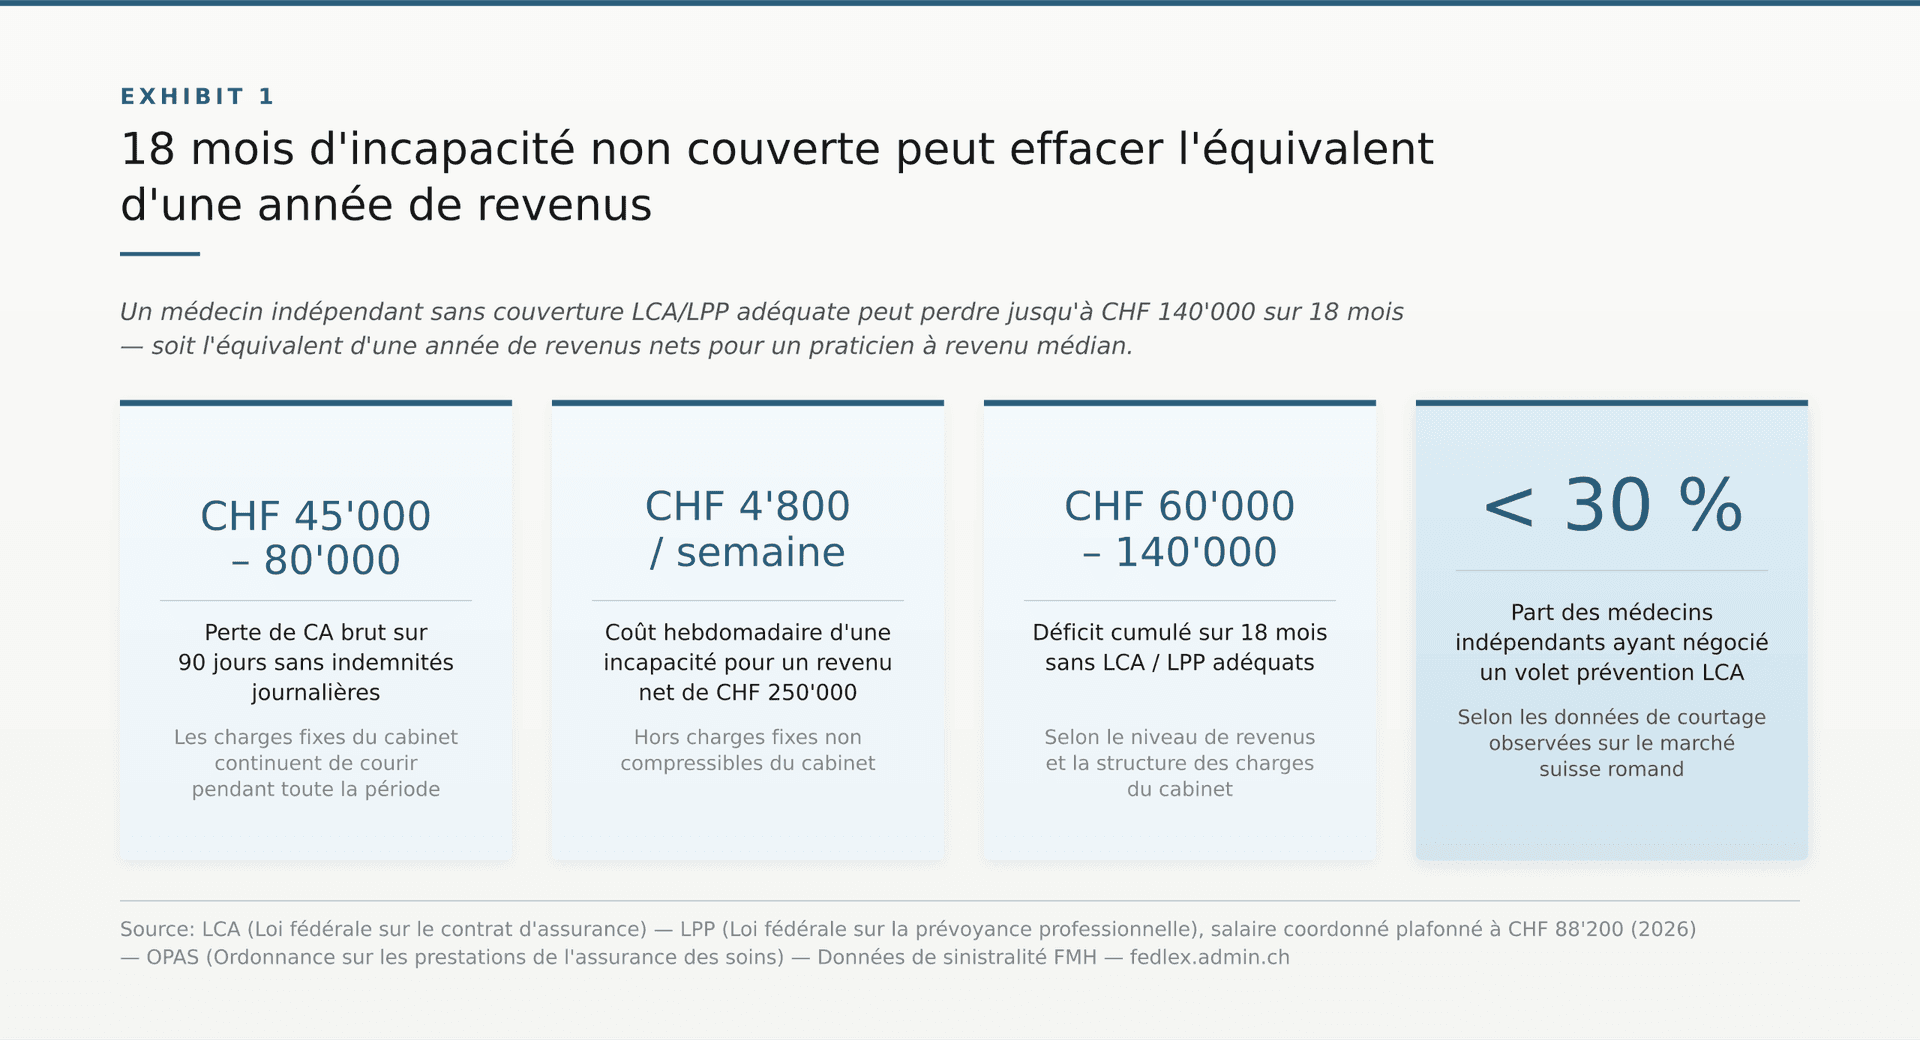
An independent doctor affiliated with the AVS [Old-Age and Survivors' Insurance] who suffers a 90-day incapacity without daily allowance cover loses on average CHF 45,000 to CHF 80,000 in gross turnover — whilst the practice's fixed costs continue to accrue. For an established practitioner, health prevention is not a matter of lifestyle hygiene: it is a risk-management line item on a par with professional liability cover or the practice's fire insurance. What you fail to quantify today, your cash flow will quantify for you.
Preventive health assessment: what it actually costs
A comprehensive preventive health assessment — lipid profile, exercise ECG, bone densitometry, musculoskeletal disorder screening — costs between CHF 800 and CHF 2,200 depending on the provider and the canton. The LAMal [Federal Health Insurance Act] covers these procedures only above a documented risk threshold, as defined by the Ordinance on Benefits under the Compulsory Health Care Insurance (OPAS). Below that threshold, the cost remains your responsibility.
In practice, a basic cardiovascular check-up without medical justification costs CHF 300 to CHF 600 depending on the canton. In Geneva, several centres offer modular assessments billed outside LAMal at between CHF 450 and CHF 1,800. In Zurich, hospital packages range from CHF 700 to CHF 2,500 for what is termed an executive health assessment.
These amounts are entirely your responsibility as a self-employed non-salaried practitioner, unless your supplementary LCA policy includes a prevention component — something that fewer than 30% of independent doctors explicitly negotiate at the point of subscription, according to brokerage data observed in the French-speaking Swiss market.
Health prevention for doctors: quantifying practice risk in 2026 — 18 months of uncovered incapacity can wipe out the equivalent of a full year's income
Loss of earnings, LCA, LAA: who covers what when you fall ill?
As an independent doctor, you are not subject to the LAA [Federal Accident Insurance Act] on a compulsory basis for occupational accidents — that obligation applies only to employees. You must therefore take out accident and illness cover under the LCA, in the form of a private loss-of-earnings insurance policy.
A common misconception: the LAMal covers your medical treatment, but it never compensates your loss of income. That role falls to the LCA, with contractual terms that vary from one insurer to another. The waiting period, exclusions for pre-existing conditions, the daily benefit cap and the maximum benefit duration are all negotiable — and are frequently under-negotiated.
A 30-day waiting period reduces the premium by approximately 20% compared with a 7-day waiting period. Calibrate that period according to your available cash reserves, not according to the lowest premium. For a doctor generating CHF 250,000 in net annual income, each week of incapacity represents approximately CHF 4,800 in lost income — excluding the non-compressible fixed costs of the practice.
For further detail on the LCA mechanisms applicable to practitioners, the article on supplementary health insurance in Switzerland (LCA guide 2026) sets out the contractual clauses to verify before signing.
Is your LPP calibrated for 6 to 18 months of incapacity?
The statutory LPP minimum guarantees a disability pension, but its amount is calculated on the co-ordinated salary — a concept that applies poorly to a self-employed person. As a doctor affiliated on a voluntary basis with a pension fund or through a collective foundation, your LPP disability cover depends on your fund's regulations, not on a uniform federal scale.
The co-ordinated LPP salary for 2026 is capped at CHF 88,200. If your net income exceeds that threshold — as it does for the majority of FMH doctors in private practice — the supra-mandatory portion of your LPP determines the bulk of your disability protection. Yet that portion is frequently under-capitalised among self-employed practitioners who joined a collective fund late or who opted for minimum contributions in order to reduce their short-term tax burden.
18 months of incapacity not covered by LCA daily allowances, combined with an insufficient LPP pension, can generate a shortfall of CHF 60,000 to CHF 140,000 depending on income level and the cost structure of the practice. This figure should be cross-referenced with the actuarial statement from your fund — a document that your LPP foundation is required to provide on request.
Cardiovascular conditions and musculoskeletal disorders: the two
According to FMH data on claims among independent doctors, cardiovascular conditions and musculoskeletal disorders (MSDs) together account for more than 60% of prolonged work incapacities among practitioners over the age of 45. These are not theoretical figures: they are the two areas in which LCA insurers most frequently apply exclusions at the time of subscription.
An untreated carpal tunnel syndrome in a surgeon or a general practitioner performing technical procedures can lead to a partial incapacity of 40 to 70%, with direct consequences for Tardoc turnover — every value point not billed represents a net loss for the practice.
On the cardiovascular side, an annual exercise ECG costs between CHF 180 and CHF 350 outside LAMal. Set against the cost of a 60-day incapacity (approximately CHF 30,000 to CHF 50,000 in lost gross turnover), that figure represents a risk-to-cost ratio that requires no further comment.
The frequency of MSDs among doctors is correlated with the duration of consultations carried out standing and with working postures — factors that LCA insurers specialising in medical professions are beginning to incorporate into their pricing, in particular for anaesthetists and surgeons.
Daily allowances: what your LCA contract actually covers
Three weeks of practice closure — 21 days — represents approximately CHF 12,000 to CHF 18,000 in unbilled Tardoc receipts for a sole-practitioner general doctor. Does the LCA daily allowance contract you have taken out cover that amount, or does it cap at 80% of the insured income declared at the time of subscription?
The majority of contracts on the Swiss market are based on the net income declared to the AVS in the year of subscription. If your activity has grown since then, the insured amount may be undersized. An annual review of the insured capital is technically possible with most LCA insurers — it is rarely triggered automatically.
Another contractual point to verify: the definition of work incapacity used. Some LCA contracts apply a strict definition (incapacity to practise your speciality), others a broad definition (any gainful activity). For a specialist FMH doctor, the difference is substantial in the event of partial MSD or a psychiatric condition.
For details on the health cover applicable to healthcare professionals in Switzerland, the article on health insurance in Switzerland for healthcare professionals sets out the LAMal/LCA interplay to be aware of before negotiating any contract.
Tax deductibility of preventive procedures for a self-employed
As a self-employed AVS-affiliated practitioner, you may deduct health and accident insurance premiums from your taxable income up to the cantonal ceilings. For 2026, the federal deduction ceiling for a single person is CHF 1,800 (IFD [Federal Direct Tax]), but cantons apply their own scales.
Vaud allows a deduction of up to CHF 3,600 for health insurance premiums for a self-employed person without children. Geneva applies a flat-rate system that allows a self-employed person to deduct up to CHF 6,000 in combined health and accident premiums. These cantonal differences can represent several hundred CHF in tax saved annually — which is not negligible when rationalising preventive expenditure.
Voluntary LPP contributions (supra-mandatory portion) are fully deductible from AVS income and from cantonal and federal tax. For a doctor in the 35% marginal tax bracket, purchasing CHF 20,000 of LPP gap cover effectively costs CHF 13,000 after tax deduction — whilst simultaneously strengthening disability cover.
By contrast, health assessments paid outside LAMal (cardiovascular check-up, preventive musculoskeletal assessment) are not deductible as professional expenses in the strict sense — unless they are documented as necessary for the exercise of the profession in a reasoned file submitted to the cantonal tax authority. This approach is possible but not guaranteed, and varies according to cantonal practice.
Conclusion: calculate your actual exposure before the end
The risk of work incapacity for an independent doctor is not an abstract risk. Between cardiovascular conditions, MSDs and professional burnout, the probability of an absence of more than 30 days before the age of 60 exceeds 35% according to claims statistics from LCA funds specialising in medical professions.
Every week without a review of your LCA contract, without verification of the insured capital and without an assessment of your supra-mandatory LPP, represents unquantified exposure. medcourtage.ch offers a targeted cover audit for FMH doctors: waiting period, daily benefit amount, definition of incapacity, LCA/LPP interplay. Take 20 minutes before the end of this quarter to submit your situation — the analysis is free of charge, and the adjustments required are often less costly than you might expect.
"The information presented is provided for informational purposes only and does not constitute medical, legal or financial advice. MedCourtage, FINMA-authorised broker no. F01502264, recommends consulting a qualified professional before making any personal decision regarding health or insurance."
FAQ
No. Unlike employees, a self-employed doctor affiliated with the AVS is not subject to the LAA or to any compulsory loss-of-earnings cover. Protection against work incapacity falls under an LCA insurance policy taken out voluntarily. Without a policy in force, every day of absence is entirely at your own expense, including the practice's fixed costs.
The optimal waiting period depends on your available cash reserves, not on the premium level. A 30-day waiting period reduces the premium by approximately 20% compared with a 7-day waiting period. If your liquidity reserve covers two months of fixed costs, a waiting period of 30 to 60 days is generally economically justified.
Partially and subject to conditions. The LAMal reimburses certain screening procedures defined by the OPAS only above a documented risk threshold. A preventive cardiovascular assessment without an identified risk factor remains your responsibility: between CHF 300 and CHF 600 depending on the provider and the canton.
An independent doctor's LPP protection depends on the regulations of their pension fund — there is no automatic compulsory LPP cover for non-employees. The co-ordinated LPP salary for 2026 is capped at CHF 88,200. Beyond that, only the supra-mandatory portion of your pension fund guarantees the disability pension, and it is frequently under-capitalised among self-employed practitioners who joined late.
Yes, in full. LPP gap purchases and supra-mandatory contributions are deductible from AVS income and from cantonal and federal tax. For a doctor in the 35% marginal tax bracket, a purchase of CHF 20,000 represents an effective cost of approximately CHF 13,000 after tax deduction, whilst improving disability cover.
Yes, significant ones. The federal IFD ceiling is CHF 1,800 for a single person. Vaud allows up to CHF 3,600, and Geneva permits a self-employed person to deduct up to CHF 6,000 in combined health and accident premiums. These differences can generate several hundred CHF in annual tax savings depending on the canton of establishment.